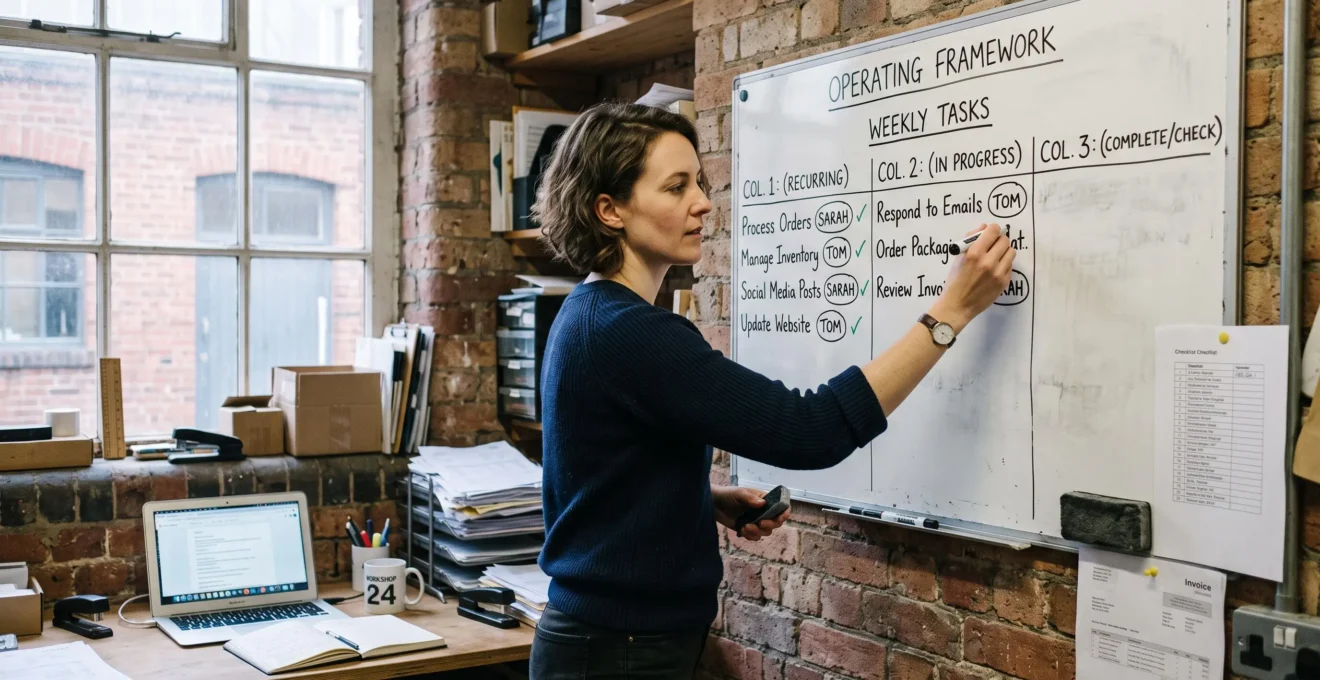
A small business operating framework establishes who is responsible for recurring activities, how routine work should happen and which decisions employees can make without consulting the founder. It replaces informal assumptions with a manageable set of responsibilities, checklists, review routines and decision rules.
For a growing UK business, the difficulty is rarely that nobody works hard enough. Customer requests, supplier payments, payroll information and operational decisions often compete for attention without a clear system determining who should handle them. The founder becomes the default decision-maker, while important tasks depend on individual memory.
The solution does not require a large operations manual or additional management layers. A useful starting point is a responsibility register, concise process instructions, a schedule of critical activities and a small number of measurable targets. Each component should make daily work easier rather than create another administrative obligation.
The framework should also distinguish operational ownership from legal accountability, particularly where company filings, employment responsibilities and financial controls are concerned.
Building a small business operating framework
- Assign one named, accountable owner to every critical recurring activity, even when several employees help complete it.
- Document essential processes with short, usable checklists and establish decision rules that reduce dependence on the founder.
- Review exceptions, deadlines and measurable outcomes regularly, adapting the framework when repeated problems reveal weaknesses.
- Why Do Small Teams Lose Time When Nobody Owns Recurring Tasks?
- How Can You Document Core Processes Without Slowing a Small Team Down?
- Which Business Activities Need a Named Owner in a Team of Under 10?
- What Makes an Operating Framework Stop Working as a Business Grows?
- When Should a Founder Start Formalising Day-to-Day Business Processes?
- Why Do Multi-Party Payments Become Difficult to Track?
- Which Accounting Tasks Are Most Often Missed When Roles Are Unclear?
- How Can Small Businesses Set Measurable Targets That Actually Influence Decisions?
Why Do Small Teams Lose Time When Nobody Owns Recurring Tasks?
Small teams lose time when recurring tasks have no named owner because employees cannot reliably determine who should initiate, complete or check the work. Responsibilities become shared assumptions rather than explicit commitments. This produces delayed action, repeated clarification and interruptions that affect people who are not directly responsible for the task.
Consider a customer invoice that needs following up. The sales employee assumes the bookkeeper is handling it, while the bookkeeper expects the founder to approve contact with the customer. Nobody deliberately abandons the task, but no individual has accepted responsibility for its outcome.
This is an example of diffused responsibility: several people recognise that work needs doing, yet none is clearly accountable for ensuring it happens.
The resulting delays can be difficult to see. Instead of an obvious failed assignment, the business experiences a growing collection of unfinished administrative activities, repeated questions and last-minute interventions.
Before hiring another employee, distinguish a capacity problem from an ownership problem. Select several recurring tasks and examine their most recent completion:
- When was the task last completed, and who performed it?
- Who decided that it needed doing?
- Was the deadline known beforehand?
- Did anyone check whether the expected outcome was achieved?
- Would the task have happened if the founder had been unavailable?
If an assigned employee consistently lacks enough working time, additional capacity or a change in priorities may be necessary. If the task is repeatedly delayed because nobody knows who should initiate it, clearer ownership is the more direct intervention.
Unassigned tasks also create an indirect coordination cost. A supplier query may trigger several messages, informal conversations and interruptions before someone accepts responsibility. These interruptions fragment other employees’ work even when the original task is relatively simple.
Prioritise tasks that repeat, affect customers or regulatory obligations, and can remain unnoticed when forgotten. Customer complaints, overdue invoices, supplier renewals and filing deadlines are practical examples.
Once responsibility is explicit, the next challenge is ensuring that employees can complete those activities consistently without relying on verbal instructions every time.
How Can You Document Core Processes Without Slowing a Small Team Down?
Small teams can document core processes without slowing operations by creating short checklists while employees perform the work. Each document should identify the trigger, essential steps, responsible owner and expected result. Focus first on activities where mistakes are costly, knowledge is concentrated in one person or instructions are difficult to reconstruct.
The objective is minimum viable process documentation, not a comprehensive manual describing every possible situation.
A one-page checklist might be enough to explain how to onboard a new customer, process a supplier invoice or respond to an urgent operational issue. Employees should be able to consult it during the activity rather than study it beforehand.
A useful process record contains the following information:
- Trigger: what event or schedule starts the activity.
- Owner: who is accountable for completion.
- Steps: the essential actions in the correct order.
- Decision point: when escalation or approval is required.
- Completion evidence: what confirms the task is finished.
- Document owner: who updates the instructions when circumstances change.
Capture the process while someone completes it. An employee processing a customer refund, for example, can record the actual checks, approval requirements and recordkeeping steps as they occur. This avoids scheduling a separate documentation exercise based on imperfect recollection.
The London Borough of Bromley‘s business continuity guidance similarly emphasises identifying critical activities, defining responsibilities and keeping operational plans simple. Its focus is disruption planning, so it should not be treated as evidence that any particular everyday documentation format is universally superior.
Start with processes that are particularly vulnerable to failure: activities performed under time pressure, those that depend on an experienced employee and those involving information that cannot easily be recovered afterwards.
Documentation also requires maintenance. An outdated instruction can mislead a new employee who assumes it still reflects current practice. Establish a revision trigger when software changes, responsibilities move, regulations change or a documented step proves unreliable.
For critical procedures, retain a periodic check as well. Event-triggered updates are useful, but they cannot identify every change that nobody noticed.
Create a usable process checklist in five actions
- Choose one recurring activity that has caused confusion. Produce a short record of the problem and its operational impact.
- Observe the next real execution. Produce a numbered list of the essential steps actually performed.
- Record the accountable owner, backup contact and approval boundary. Produce a completed responsibility header.
- Define how successful completion is recorded. Produce a specific completion check or evidence field.
- Ask another employee to follow the instructions and note unclear steps. Produce a corrected, dated version of the checklist.
Once the instructions are accessible, the business must decide which activities genuinely require an accountable owner and where responsibilities should be separated for control purposes.
Which Business Activities Need a Named Owner in a Team of Under 10?
In a team of fewer than ten people, activities need named owners when an omission could affect customers, cash flow, security or legal compliance. Frequent tasks and activities requiring several employees also benefit from explicit ownership. One person should be accountable for each outcome, even when others execute individual steps.
The goal is not to give every minor action a formal title. It is to prevent important work from depending on assumptions about who will remember to do it.
Use three criteria when deciding whether to assign an owner: the consequence of a missed task, its frequency and the coordination required to complete it.
The following responsibility register illustrates where a small UK business might begin. The roles are examples, not mandatory job titles.
| Business activity | Example accountable owner | Essential control |
|---|---|---|
| Customer enquiries and complaints | Customer service lead | Unresolved cases reviewed against an agreed deadline |
| Sales invoicing and debt collection | Finance administrator | Outstanding balances reviewed regularly |
| Supplier relationships and renewals | Operations lead | Upcoming commitments and changes recorded |
| Payroll information | Payroll coordinator | Inputs checked before submission and payment |
| Companies House filings | Director or designated administrator | Director oversight and filing confirmation |
| VAT administration, where applicable | Finance lead | Deadline tracking and reconciliation |
| Customer data access | Designated data or operations lead | Access permissions reviewed when roles change |
| Cybersecurity and backup checks | Designated IT owner | Critical controls tested and exceptions escalated |
These responsibilities may be combined in a very small business. The essential distinction is between the person who performs an activity and the person who is accountable for its outcome.
For example, an accountant may prepare a filing while a company director remains responsible for appropriate oversight. Similarly, several employees may respond to customers, but one named owner should monitor whether unresolved cases receive attention.
Financial responsibilities also require appropriate checks and balances. Separation of duties reduces the risk that an error or unauthorised transaction will pass unnoticed because the same person initiates, approves and reviews every stage.
Where staffing permits, the employee preparing payments should not also be the sole person authorising them and verifying the bank reconciliation. If complete separation is impractical, a director or another authorised individual can independently review the relevant records.
Ownership must remain workable during absences. Assign a backup who can perform essential tasks, while retaining a clear escalation path if the accountable owner becomes unavailable.
These assignments should not be treated as permanent. As the business grows, responsibilities that once fitted naturally within one role may begin to exceed that person’s capacity.
What Makes an Operating Framework Stop Working as a Business Grows?
An operating framework stops working when the volume and complexity of decisions exceed the responsibilities, processes and approval rules originally designed for the business. Growth creates more exceptions, dependencies and competing priorities. Warning signs include founder approval bottlenecks, repeated errors despite written procedures and employees relying excessively on informal explanations.
A framework built for three employees may operate smoothly because everyone has direct access to the founder and understands how colleagues work. As additional employees join, the same informal coordination requires more conversations and assumptions.
The framework usually does not fail suddenly. It deteriorates through small exceptions that gradually become standard practice.
A purchasing rule might originally require approval for unusual expenses. Over time, employees begin requesting approval for routine purchases because the distinction is unclear. Eventually, the founder becomes responsible for decisions that other people could safely make.
Three common pressure points deserve attention:
- Decision bottlenecks: ordinary work waits for the founder or one manager to respond.
- Overloaded roles: an individual retains several responsibilities even after the combined workload becomes difficult to manage.
- Informal knowledge: new recruits require repeated verbal explanations because documents no longer reflect actual practice.
These symptoms should prompt an operating review rather than an automatic expansion of policies.
For instance, if customer refunds are repeatedly delayed, investigate whether the problem is unclear approval authority, unavailable information, insufficient staffing or an ineffective workflow. Each cause requires a different response.
A written refund threshold may resolve an approval bottleneck, whereas an additional checklist will do little to address inadequate staffing.
The key trade-off is between premature bureaucracy and organisational debt. Formalising every minor action too early creates unnecessary approvals and maintenance work. Waiting until failures are widespread can leave the business dependent on undocumented practices that are difficult to replace.
A practical approach is to increase formalisation in response to repeated errors, avoidable delays and growing dependencies, rather than relying on headcount alone.
Review the framework whenever a new management layer appears, responsibility for a critical activity changes or several employees begin handling work previously completed by one person.
Growth makes adjustment necessary, but founders do not need to wait for expansion before introducing their first operating rules.
When Should a Founder Start Formalising Day-to-Day Business Processes?
A founder should begin formalising daily processes when routine decisions repeatedly depend on their availability or an important task becomes vulnerable to absence, confusion or forgetfulness. The trigger is operational dependence, not a particular revenue figure or employee count. Basic responsibilities and instructions are especially useful before the first employee joins.
Many founders manage early operations through personal memory, direct customer relationships and quick conversations. This can work when one person handles most decisions and the business has limited complexity.
The problem emerges when other employees cannot act confidently without asking for information that the founder has never documented.
To assess founder dependence, record the decisions made during a typical working week. Group them into three categories:
- Decisions requiring the founder’s judgement because of their strategic, financial or legal significance.
- Routine decisions another employee could make using an agreed rule.
- Decisions that require escalation only when a predefined exception occurs.
Consider a hypothetical business where the founder approves every replacement order from an established supplier. If ordinary orders follow known limits and specifications, a documented purchasing rule may allow an authorised employee to act independently. Exceptions involving new suppliers or spending outside agreed limits can remain subject to approval.
This approach establishes decision rights: who can decide, within which boundaries and when an issue must be escalated.
Formalising before recruitment can also simplify onboarding. A newcomer receives clear instructions rather than learning all routines by observing the founder and repeatedly asking questions.
However, attempting to document every possibility before hiring can become counterproductive. Concentrate on the processes the new employee will actually use and those where misunderstanding would carry meaningful consequences.
Waiting for a serious operational failure is equally problematic. Rules written during an emergency may be excessively restrictive because they address the immediate incident rather than its underlying cause.
When a failure occurs, identify which instruction, responsibility or decision boundary was missing. Make the smallest effective change and assess whether employees can follow it during normal operations.
Financial workflows are particularly useful candidates for early formalisation because several parties, dates and approval steps can make mistakes difficult to trace.
Why Do Multi-Party Payments Become Difficult to Track?
Multi-party payments become difficult to track because suppliers, subcontractors, payment platforms and internal finance teams may record the same transaction at different times and in different systems. Payment initiation, bank settlement and accounting entry dates can differ. Without a central record and clearly divided responsibilities, discrepancies may remain unnoticed until reconciliation.
A payment involving several parties has more points at which information can diverge. A supplier may consider an invoice overdue while the business believes it has already transferred the funds. A payment intermediary may still be processing the transaction, or a finance administrator may not yet have recorded it.
Understanding the dates involved is essential:
- Payment date: the date the business initiates or makes a payment, as defined in the relevant record.
- Value date: the date a bank applies value to a transaction under its processing arrangements.
- Accounting entry date: the date used to record the transaction in the accounting system.
These dates do not necessarily coincide. Their differences can create temporary reconciliation discrepancies without proving that money is missing.
Rather than reconstructing payment histories from separate email threads, maintain one authorised tracking register.
| Field | Purpose | Example entry |
|---|---|---|
| Payment reference | Connects invoice, transaction and correspondence | PAY-001 |
| Counterparty | Identifies the recipient | Supplier A |
| Expected payment date | Supports scheduling | Agreed due date |
| Current status | Shows progress | Expected, sent, disputed or reconciled |
| Evidence | Supports investigation | Bank reference and invoice |
| Accountable owner | Identifies who resolves exceptions | Finance lead |
This example is a proposed operational register, not a prescribed regulatory format. Businesses should ensure their records also satisfy relevant accounting and recordkeeping requirements.
Assign one owner to monitoring the payment register and reconciliation process. That person should maintain visibility over outstanding items and ensure discrepancies are investigated.
However, operational ownership should not eliminate independent financial control. Wherever practicable, the person authorising expenditure should be different from the person reviewing whether the resulting transactions have been recorded and reconciled correctly.
When staffing makes full separation difficult, an independent review by a director or another authorised person provides an additional check.
Disputed payments should remain visible until resolved. Marking an item as sent is not equivalent to confirming that the intended recipient received and reconciled the payment.
The same discipline becomes more important when financial activities are tied to UK statutory reporting, payroll or pension obligations.
Which Accounting Tasks Are Most Often Missed When Roles Are Unclear?
When accounting responsibilities are unclear, UK small businesses are vulnerable to overlooking periodic filings, payroll submissions, VAT obligations and workplace pension administration. These tasks follow different schedules and depend on the business’s circumstances. Although no single category can be identified as the most frequently missed from the available evidence, each warrants explicit ownership and deadline monitoring.
The risk is that employees interpret outsourced bookkeeping or accounting support as a complete transfer of administrative responsibility. A business may have an accountant preparing records but no internal owner checking that necessary information was supplied or submissions completed.
For limited companies, Companies House guidance on director responsibilities makes clear that appointing an accountant or another professional does not remove directors’ legal responsibility for company records, accounts and required filings.
That distinction does not mean a director becomes personally liable for every company debt or penalty. It means that delegation must be accompanied by appropriate oversight of the director’s statutory obligations.
The following activities deserve attention when developing a UK compliance calendar:
| Activity | When relevant | Ownership check |
|---|---|---|
| Companies House confirmation statements and annual accounts | UK limited companies | Named filing owner, director oversight and submission confirmation |
| VAT returns and payments | VAT-registered businesses subject to the relevant requirements | Return preparation, payment and reconciliation allocated |
| VAT payments on account | Businesses to which the applicable payment-on-account rules apply | Applicability and payment schedule specifically verified |
| PAYE Real Time Information submissions | Employers operating relevant PAYE payroll arrangements | Payroll data and submission responsibilities assigned |
| Self Assessment | Individuals or businesses with an applicable filing obligation | Filing responsibility established for the relevant taxpayer |
| Workplace pension duties | Employers subject to applicable automatic enrolment requirements | Eligibility monitoring, contributions and periodic duties assigned |
These activities do not all apply to every business. VAT status, employment arrangements, legal structure and individual tax circumstances determine the relevant obligations.
HMRC provides an official tax deadline checker covering VAT, PAYE, Self Assessment and certain Construction Industry Scheme obligations. Businesses can use the HMRC tax filing and payment deadline checker to identify applicable dates based on their circumstances and add them to a compliance calendar.
Workplace pension administration also requires continuing attention. The Pensions Regulator‘s guidance identifies ongoing employer duties involving employee eligibility, contributions and records, alongside periodic re-enrolment and re-declaration requirements. Not all workers are subject to identical enrolment requirements.
An annual compliance review should begin by identifying the business’s actual obligations rather than copying a generic list of deadlines. For each obligation, record the filing or payment requirement, applicable due date, operational owner, external adviser where relevant and person responsible for confirming completion.
For example, an accountant might prepare a VAT return while the finance lead supplies supporting information, an authorised person approves the submission or payment and a designated reviewer checks the confirmation. The precise division should be documented and agreed with the service provider.
Where resources permit, another person should cross-check upcoming deadlines and evidence of completion. This creates a safeguard against omissions that might otherwise remain invisible until a notice, enquiry or penalty arrives.
Review the calendar when business circumstances change, including the first employee joining, a change in VAT registration status or a restructuring of accounting responsibilities.
With critical responsibilities assigned and deadlines visible, the final step is measuring whether the operating framework is producing reliable decisions and outcomes.
Key takeaways for owner-managers
- Review operational exceptions before adding more rules: a recurring delay may reflect missing authority, insufficient capacity or an ineffective process.
- Connect financial controls and compliance deadlines to named owners, documented checks and evidence of completion.
- Measure outcomes that can trigger a specific management action rather than collecting figures that merely describe business activity.
How Can Small Businesses Set Measurable Targets That Actually Influence Decisions?
Small businesses can set targets that influence decisions by linking each measure to a named process owner, a review frequency and a predetermined response when performance falls outside an acceptable range. A useful target changes an operational decision. A figure that employees merely report, without acting on it, provides limited management value.
Many businesses track figures because they are easy to collect. Website visitors, social media followers and the volume of completed activities may indicate activity or interest, but they do not automatically reveal whether operations are reliable or financially sustainable.
A decision-oriented metric identifies an outcome the responsible person can influence and clarifies what should happen when performance changes.
Consider the difference between reporting the number of customer enquiries received and measuring how many remain unresolved beyond the agreed response period. The first describes workload. The second can reveal a service problem requiring action.
To make each target operational, define four elements:
- Owner: the individual accountable for reviewing and responding to the result.
- Measure: a consistently defined outcome that can be checked using reliable records.
- Review frequency: the interval at which new information can meaningfully change a decision.
- Response rule: the action or investigation triggered when the agreed limit is exceeded or missed.
The appropriate threshold should reflect business circumstances, customer commitments, regulatory requirements where relevant and observed performance. There is no universal percentage or deadline suitable for every small business.
The examples below show how existing operational responsibilities can become decision-oriented measures.
| Measure | Accountable owner | Decision triggered |
|---|---|---|
| Overdue customer invoices | Finance lead | Review collection activity and investigate disputed balances |
| Unresolved customer cases | Customer service lead | Reallocate attention or investigate recurring causes |
| Late recurring tasks | Operations lead | Check ownership, workload and process instructions |
| Unreconciled payments | Finance lead | Investigate exceptions and obtain independent review |
| Decisions awaiting founder approval | Founder or operations lead | Assess whether decision authority can be delegated |
| Gross margin against plan | Business owner | Review pricing, costs and product or service mix |
These are candidate measures rather than fixed targets. A business should select the few that reveal its most significant operational risks and decisions.
For example, a team experiencing repeated fulfilment delays might monitor orders completed by their agreed dispatch dates. If performance deteriorates, the operations owner investigates whether the underlying cause is supplier availability, unclear handovers or insufficient capacity.
Without a defined response, the measurement risks becoming another recurring reporting task.
Review frequency should also match the decision. An unresolved urgent customer issue may require daily attention, whereas a broader profitability measure might be reviewed over a longer accounting period.
The operating framework is functioning when employees can identify a problem, understand their authority and take the next appropriate action without unnecessary escalation.
Begin with one critical workflow this week. Name its owner, document its essential steps, clarify the approval boundary and choose one measure that will reveal whether it works. Review the outcome after the next few executions, then extend the approach to the next priority process.
Can a business operating framework work without a dedicated operations manager?
Yes. A small business can distribute operational responsibilities among existing employees, provided each critical activity has an accountable owner and clear escalation arrangements. The founder may retain overall oversight while authorised employees manage recurring work. A dedicated operations manager becomes a consideration when coordination responsibilities exceed the capacity of existing roles.
What is the difference between a responsibility register and a process checklist?
A responsibility register identifies who is accountable for an activity. A process checklist explains how that activity should be performed, including essential steps, decisions and completion evidence. Both are useful: assigning an owner without instructions can leave execution inconsistent, while documenting instructions without ownership can leave the process unattended.
How should a small business handle responsibilities during employee absences?
Identify a trained backup for critical activities and ensure that necessary instructions and authorised access arrangements are available. Specify which decisions the backup can make and when escalation is required. Sensitive financial, customer or administrative access should remain subject to appropriate controls rather than being shared informally.
Does outsourcing bookkeeping remove a UK company director’s filing responsibilities?
No. For a UK limited company, directors retain statutory responsibilities for company records, accounts and required Companies House filings even when professionals assist with the work. A written arrangement should clarify who prepares, submits and verifies each obligation. Other tax and employment responsibilities depend on the legal requirements applicable to the business.
How often should a small business review its operating framework?
Use a review frequency appropriate to operational risk and how quickly decisions need to be made. Critical tasks may require daily or weekly checks, while broader responsibility arrangements may be reviewed less frequently. Trigger an additional review when an employee joins or leaves, a recurring failure appears, software changes or decision-making becomes unnecessarily dependent on the founder.