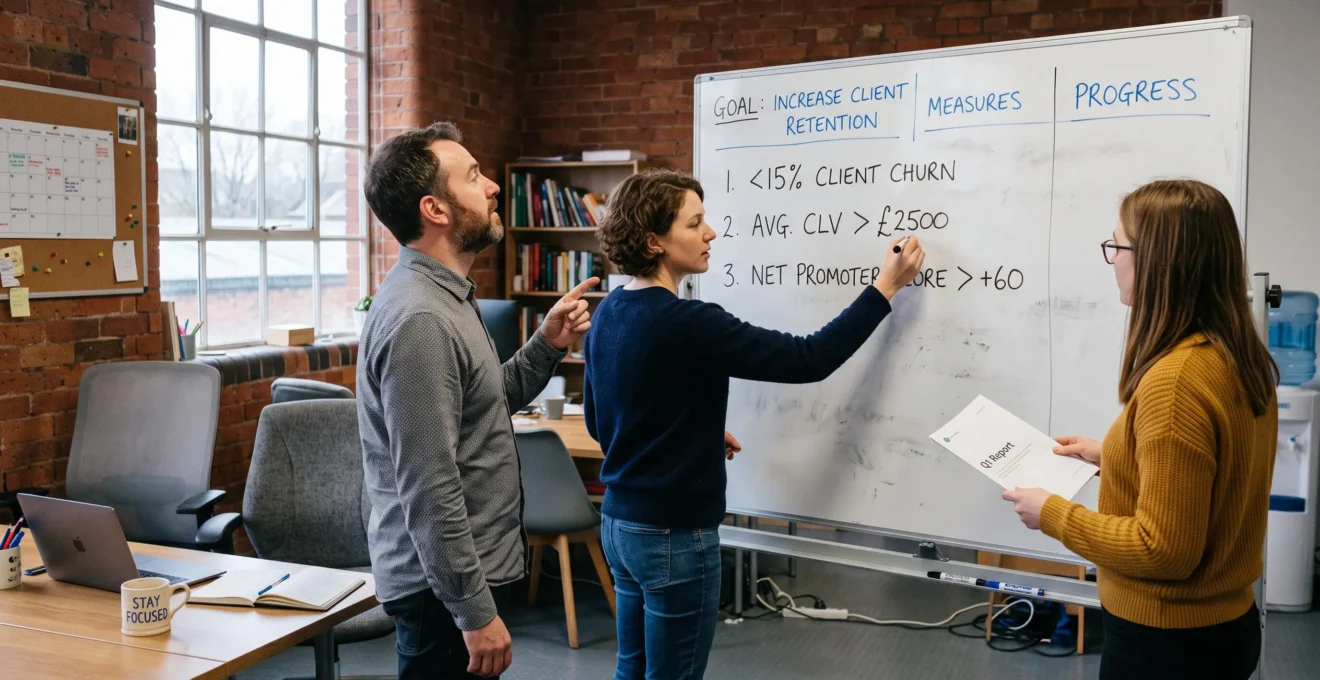
A small business can have ambitious goals, motivated employees and a carefully written business plan without making better decisions. The missing link is often a measurable target that tells someone what to do differently when circumstances change.
Goals such as “increase sales”, “improve customer service” or “build brand awareness” describe desirable outcomes. They do not explain which actions deserve priority, what evidence indicates progress or when the business should change course.
Effective performance targets bridge that gap. They connect a defined result to a manageable set of indicators, clarify who can influence those indicators and establish the decisions that follow from them. For a UK small business with limited time and reporting capacity, the challenge is not collecting more data. It is identifying the few measurements that are worth acting on.
The practical test is straightforward: if a target changes neither a decision nor a behaviour, it is not yet an effective management tool.
How to make business targets useful
- Translate each broad ambition into a specific decision, an outcome measure and one or two indicators that can influence it.
- Define each measure consistently and check whether meeting the target could damage quality, profitability or teamwork.
- Review indicators at the speed decisions can change, and revisit the underlying goals when business assumptions shift.
- Why Do Broad Business Goals Rarely Change Team Behaviour?
- How Can You Turn a Business Goal Into 3 Useful Performance Measures?
- Activity Targets or Outcome Targets: Which Should a Small Team Track?
- Which Performance Targets Can Accidentally Damage a Business?
- How Often Should a Small Business Review Its Key Targets?
- How Can You Turn a 3-Year Business Ambition Into Practical Goals?
- How Can You Turn Brand Awareness Into a Measurable Communication Objective?
- How Can a UK Founder Build a Business Plan That Remains Useful After Launch?
Why Do Broad Business Goals Rarely Change Team Behaviour?
Broad business goals rarely change behaviour because employees cannot reliably translate them into decisions they control. An instruction to “grow the business” expresses direction but does not establish which customers to prioritise, which activities to increase or which trade-offs to accept. Even a committed team can continue working exactly as before when the expected behavioural change remains undefined.
Consider a hypothetical UK business where the owner announces that growth is the priority. The salesperson interprets this as winning more customers. The operations employee focuses on processing orders faster. The finance manager concentrates on protecting cash. Each interpretation is reasonable, yet the resulting decisions can pull in different directions.
The underlying problem is not necessarily poor communication or insufficient motivation. It is the absence of an agreed relationship between the strategic goal and everyday choices.
An ambition defines the direction; an actionable target helps choose between alternatives. For example, “increase sales” becomes more useful when expressed as “improve repeat-purchase revenue without reducing gross margin”. The revised statement gives the team criteria for evaluating whether a promotion, customer segment or follow-up activity deserves attention.
A useful test is to ask what the target should change on Monday morning. Would someone call a different customer, revise a quotation, adjust a schedule or stop an unproductive activity? If nobody can identify a plausible decision, the goal still needs translating.
Professional guidance supports the importance of this connection. The CIPD factsheet on performance management explains that organisational objectives and performance indicators need to become clear expectations for employees. It also distinguishes task performance from the wider behaviours and adaptability that contribute to effective work.
Without a shared interpretation, teams may optimise different measures while believing they are working towards the same goal. The owner may then conclude that targets are ineffective, when the real issue is that the target never established a common basis for decisions.
Once the desired decision is clear, the next task is to select measurements that reveal whether the business is moving in the intended direction.
How Can You Turn a Business Goal Into 3 Useful Performance Measures?
To turn a business goal into three useful performance measures, first identify the decision the goal should influence. Then select one outcome indicator that confirms progress and one or two leading indicators that help predict or influence that outcome. Define each calculation, assign responsibility and agree what management action should follow when a measure changes.
Start with a hypothetical independent service business whose goal is to generate more revenue from existing customers. The owner needs to decide whether to invest additional staff time in customer follow-up.
Three measures could make that decision more informed:
- Repeat-customer revenue: the total revenue received from customers who have purchased previously, measured monthly. This indicates whether the intended commercial result is materialising.
- Eligible customers contacted: the proportion of customers due for a relevant follow-up who receive one within the agreed period. This measures an activity the team controls.
- Follow-up conversion rate: the proportion of eligible follow-up contacts that lead to a qualifying repeat purchase within a defined period. This helps distinguish useful outreach from activity that produces little commercial value.
This example illustrates a practical framework, not a scientifically established optimal combination. Three measures provide a manageable starting ceiling for a small team, but some decisions need fewer, and more complex operations may legitimately need additional indicators.
The crucial requirement is consistency. If one employee counts a repeat customer after any previous enquiry while another requires a completed purchase, their figures cannot be compared meaningfully.
Each measure therefore needs a written definition specifying its numerator, denominator where relevant, source data, reporting period and owner. The resulting numbers should allow two employees to calculate the same value from the same records.
Before approving a measure, also identify its intended response. If follow-up activity increases but repeat revenue remains unchanged, management might review customer eligibility, offer relevance or contact quality rather than simply demanding more calls.
Build a three-measure target sheet
- Write one business goal as a specific result with a review horizon. Deliverable: a single-sentence goal statement.
- Identify one decision the goal should influence. Deliverable: a written decision question with at least two possible actions.
- Select one outcome measure and up to two leading indicators. Deliverable: a short KPI list stating the purpose of each measure.
- Document each measure’s calculation, data source, reporting period and accountable owner. Deliverable: a shared measurement dictionary.
- Define what should trigger investigation or a change of action, including a quality or financial safeguard. Deliverable: a target sheet with documented decision rules.
Setting a numerical threshold also requires judgement. Historical performance, available capacity and commercial constraints provide a stronger basis than choosing an impressive figure without supporting evidence.
The distinction between outcome and leading measures matters because they provide different types of information at different stages of the decision process.
Activity Targets or Outcome Targets: Which Should a Small Team Track?
A small team should usually combine activity and outcome targets rather than relying exclusively on either. Activity measures are most useful when employees control the action but the result takes time to emerge. Outcome measures show whether the activity is producing the intended value. The right balance depends on how much influence the team has over each measure and how quickly feedback becomes available.
Consider a hypothetical business that sells maintenance contracts. Tracking only monthly sales reveals whether contracts were won, but may not explain an emerging shortage of qualified opportunities. Tracking only telephone calls shows whether employees were active, but not whether those conversations involved suitable prospects.
The two measures answer different questions, as the following comparison shows.
| Decision factor | Activity targets | Outcome targets |
|---|---|---|
| What they measure | Actions completed by the team | Results achieved by the business |
| Typical example | Qualified follow-up conversations | New contracts signed |
| Direct employee control | Usually greater | Often shared with customers or external conditions |
| Feedback timing | Potentially immediate | May arrive after a delay |
| Main limitation | High activity can produce little value | Results may appear too late to guide action |
| Best management use | Adjusting effort and execution | Assessing effectiveness and priorities |
A useful structure is one outcome indicator supported by one or two activities that plausibly contribute to it. Where the relationship is uncertain, treat the chosen activities as hypotheses to test rather than proven drivers of success.
For example, if the business aims to improve contract renewal, it might monitor renewals alongside timely customer reviews. If review completion increases but renewal performance does not, the team has learned that completing reviews alone is insufficient.
Activity measures also need a quality safeguard. A call-count target could be paired with a definition of a qualified conversation, while a production-volume target could be checked against an acceptable defect rate. Otherwise, the easiest way to improve the number may be to reduce the quality of the work.
Not every role can be assessed through a simple volume target. Customer support, technical problem-solving and collaborative work may require assessments of service quality, responsiveness or judgement alongside quantitative measures.
However, even a well-balanced set of measures can produce damaging incentives if the team is rewarded for the number without considering its wider consequences.
Which Performance Targets Can Accidentally Damage a Business?
Performance targets can damage a business when improving the reported number requires behaviour that harms profitability, customer relationships, work quality or staff effectiveness. Revenue, customer acquisition and employee utilisation targets are particularly vulnerable when used without safeguards. Before adopting any target, managers should examine what behaviour it encourages, what that behaviour costs and which important outcomes the measurement overlooks.
Consider a hypothetical small UK retailer with a revenue target but no margin safeguard. Offering increasingly large discounts could help employees achieve the sales figure while leaving the business with less gross profit to cover operating expenses.
A customer-acquisition target presents a different risk. A team may win more accounts by pursuing customers who require unusually expensive servicing, frequent returns or substantial credit. The customer count improves even if the additional business contributes little profit.
In a professional services company, a high billable-utilisation target could discourage staff from documenting processes, developing skills or improving internal systems. Those activities do not generate immediate billable hours, yet neglecting them can undermine future capacity.
These examples illustrate a common measurement problem: the target captures one benefit while leaving an associated cost invisible.
Before introducing a target, carry out a short incentive review. Ask three questions: what will someone do more often to achieve this number, what might they stop doing, and what would the business lose if everyone pursued the target as aggressively as possible?
If the answers reveal an important unmeasured consequence, introduce a guardrail. Revenue growth might be assessed alongside gross margin. New accounts might be checked for contribution after servicing costs. Billable utilisation might be balanced with agreed time for essential development and operational improvement.
The safeguard should reflect a real commercial or operational risk, rather than becoming another arbitrary target.
The CIPD also cautions that excessive emphasis on narrow numerical targets can interfere with effective performance. Its guidance recognises that complex, collaborative and adaptive work cannot always be represented adequately by simple output counts.
This matters in small businesses where one employee may cover sales, customer service and operations. Assigning that person an aggressive sales-style target without recognising other responsibilities can create conflicting priorities and unreasonable pressure. Whether such pressure leads to staff turnover depends on circumstances; the risk should not be presented as an inevitable outcome.
A safer approach is to match measures to the work employees can influence and to review the effect of targets on the overall business, not just their individual scores.
Even carefully designed targets need a suitable review rhythm so that emerging problems are identified without encouraging constant changes in direction.
How Often Should a Small Business Review Its Key Targets?
A small business should review each performance target as frequently as new information could reasonably change a decision. Weekly reviews can suit controllable activities, monthly reviews may suit commercial outcomes, and quarterly reviews can assess whether priorities remain appropriate. These intervals are practical starting points rather than universal rules: the right frequency depends on the decision, data reliability and pace of change.
A weekly activity discussion can identify whether promised follow-ups were completed or whether operational work is accumulating. Waiting until the end of a quarter could allow a correctable problem to continue unnecessarily.
Monthly outcome reviews may be more useful for sales conversion, repeat-customer revenue or service performance where enough observations need to accumulate before a meaningful pattern becomes visible.
By contrast, reviewing an outcome too frequently can encourage reactive changes based on normal variation. A business might repeatedly revise prices or campaigns in response to a handful of transactions rather than waiting for sufficient evidence.
Reviewing too infrequently creates the opposite problem. A target designed for a particular staffing level, customer mix or trading environment may become outdated while employees continue pursuing it.
A practical review rhythm could therefore look like this:
| Frequency | Primary focus | Decision to make |
|---|---|---|
| Weekly | Controllable activities and immediate obstacles | What should the team adjust next week? |
| Monthly | Commercial outcomes and quality safeguards | Are current activities producing useful results? |
| Quarterly | Strategic priorities and key assumptions | Should resources or targets change? |
| Annually | Overall relevance of business objectives | Are these still the right goals to pursue? |
The British Business Bank guidance on reviewing a business plan discusses regular monitoring, notes that some businesses review progress every three or six months and recommends a formal review at least annually. It also recognises that significant market changes can justify an additional review.
The annual discussion should be distinct from a routine performance assessment. Instead of asking only whether the organisation achieved its targets, ask whether those targets still represent the right definition of progress.
Every review should end with a recorded decision: continue, investigate, change an activity, revise a target or reconsider an assumption. Without that decision, reporting risks becoming an administrative exercise.
Once review intervals are established, the same system can connect immediate actions to a longer-term ambition without treating the future as a fixed forecast.
How Can You Turn a 3-Year Business Ambition Into Practical Goals?
A three-year business ambition becomes practical when it is translated backwards into annual milestones, quarterly priorities and measurable short-term decisions. Begin with the desired future position, identify what must be true at each intermediate stage and connect those conditions to the indicators already used in day-to-day management. The resulting plan should make its assumptions explicit so that changing circumstances lead to informed revisions.
Imagine a hypothetical UK service business that wants to operate successfully across several regional markets within three years. Simply projecting its current revenue growth forwards would not establish how that expansion could happen.
Instead, the owner could work backwards from the desired operating model.
- Three-year ambition: establish a sustainable presence across the intended regional markets, with suitable staffing and service capacity.
- Annual milestones: demonstrate that the core service model works, build the capacity required for additional locations and validate demand in each prospective market.
- Quarterly priorities: test specific propositions, improve operating processes and decide whether available evidence supports the next expansion step.
- Short-term measures: track qualified enquiries, conversion, contribution, delivery capacity and other indicators directly relevant to the next decision.
The business should then list the assumptions behind each milestone. For example, expansion may depend on sufficient local demand, achievable pricing and access to suitably skilled staff.
These are assumptions to test, not facts established by the ambition itself. If local demand proves weaker than expected, the owner can reconsider the chosen market without abandoning the wider business direction.
Similarly, a change in recruitment costs may require a different operating model even if customer demand remains strong.
Linear extrapolation is particularly limited when growth depends on discrete changes such as hiring a new team, entering another region or changing prices. Those developments may alter both costs and capacity in ways that a simple growth percentage does not capture.
A more informative approach is to frame the ambition as a conditional scenario: what market demand, resources, capabilities and financial performance would need to exist for the intended future position to become viable?
The British Business Bank’s financial guidance reinforces the importance of revisiting planning assumptions when circumstances change. A forecast should support decisions, not become a commitment to figures that have lost their relevance.
Long-term planning becomes more credible when every major ambition has an observable path to progress. The same translation is needed for less tangible objectives, including brand awareness.
How Can You Turn Brand Awareness Into a Measurable Communication Objective?
Brand awareness becomes a measurable communication objective when a business identifies the audience it wants to reach, the channel through which that audience encounters it and an observable signal of growing familiarity. Suitable indicators may include branded search activity, relevant website visits or enquiries that mention a communication channel. The choice should reflect actual customer behaviour, not whichever metric looks most impressive.
For a hypothetical plumbing business serving a defined area in England, “increase brand awareness” provides little guidance. A more useful objective might be to improve recognition among local homeowners who could realistically become customers.
The company could investigate branded search activity, enquiries mentioning its local advertising or website visits associated with specific campaigns. Each measures a different part of the communication process.
An important distinction is whether a metric captures exposure, demonstrated interest or commercial response.
Social impressions may indicate that content was displayed, but cannot establish that the intended audience remembered the business. Branded searches may provide a stronger signal of active interest for audiences that habitually search for suppliers by name. Yet customers can buy through recommendations, telephone calls or direct visits without searching for a brand at all.
The selection test should therefore be whether the audience is likely to generate the proposed signal during its normal journey towards an enquiry or purchase. No single proxy is universally valid or compulsory.
Google‘s Search Console documentation on measuring brand awareness describes branded and non-branded query reporting. These reports help examine visibility and interactions within Google Search, but they do not measure total awareness or prove that a particular campaign caused a change.
The documentation also identifies availability limitations for lower-impression websites and certain property types. Smaller businesses should check whether the relevant reporting features are available before building objectives around them.
Geography introduces another important constraint. A UK service business operating within a limited catchment area gains little from celebrating national visibility if the additional interest comes from people it cannot serve.
Where appropriate data is available, the business can compare location-relevant enquiries or campaign responses. Google Search Console’s country-level reporting should not be mistaken for an exact measurement of branded searches within a particular town or service radius.
A useful communication target combines an audience definition, a relevant observable signal, a review period and an agreed response if the signal changes. It should also recognise that awareness indicators alone do not establish commercial return.
These objectives become easier to maintain when they sit within a business plan that is actively updated as evidence, resources and priorities change.
Key takeaways before putting the framework into practice
- A useful operating plan records the decisions behind its targets, not merely the targets themselves.
- Separating assumptions from observed results makes revisions more transparent and less disruptive.
- Formal planning documents and internal management tools should share consistent evidence while serving different purposes.
How Can a UK Founder Build a Business Plan That Remains Useful After Launch?
A UK founder can keep a business plan useful after launch by treating it as a living decision document rather than a one-off funding exercise. The operating version should bring together current objectives, key measures, financial assumptions, responsibilities and review dates. Actual results should inform revisions, while the plan retains enough continuity to show what changed and why.
A conventional business plan may describe the market, products, customers, competitive position, operations and financial forecasts. Those sections remain useful, but their value after launch depends on whether they inform present decisions.
For everyday management, a shorter operating plan can prioritise five connected elements: the business’s current objectives, the decisions those objectives influence, its performance indicators, the assumptions behind them and the next review point.
Founders should also distinguish between an internal plan and a document prepared for UK lenders or investors. An external plan generally needs to communicate the commercial proposition, market evidence, financial projections and funding rationale in a form suited to its audience. An internal plan can focus more directly on operational priorities and decisions.
The two documents should remain consistent, but they do not need identical levels of detail.
After launch, the business should compare forecasts with actual performance during its scheduled financial reviews. Rather than deleting every original projection, retain the baseline or previous forecast alongside the latest actuals and revised outlook so that differences can be understood.
For example, a founder might have expected repeat customers to account for a growing share of revenue. If actual performance falls short, the review should establish whether the assumption about retention was incorrect, the planned activities were not completed or other factors influenced purchasing behaviour.
The next action could involve improving customer follow-up, changing the forecast or reconsidering the commercial priority. Rewriting the entire plan would rarely be necessary.
The British Business Bank guidance on revising financial forecasts explains that new facts, material events and inaccurate assumptions can justify updating existing forecasts. It also distinguishes cash-flow forecasting from profit-and-loss planning, which address different aspects of financial performance.
A quarterly operating review can therefore include actual results, meaningful variances, changed assumptions and the decisions taken in response. This is a suggested management approach, not a prescribed UK reporting requirement.
Retaining a concise decision log gives subsequent reviews continuity. It allows the founder to see whether earlier changes produced the intended effect and prevents the same assumptions from being repeatedly debated without new evidence.
Choose one active business goal, write down the decision it should influence and identify the evidence needed to make that decision. Add those elements to the operating plan, assign an owner and schedule the first review. A business plan becomes useful after launch when it provides a reliable basis for the next action, not simply a record of the original intention.
What should a small business do if it has no reliable historical data?
Begin with measures that can be defined and collected consistently using existing records. Establish an initial baseline before setting demanding numerical thresholds. If the available data is incomplete, document the limitation and use early reviews to improve measurement quality rather than presenting uncertain figures as established performance.
Should every employee have an individual numerical target?
No. Individual targets are useful when employees can meaningfully influence the measured result. Collaborative, complex or adaptive work may require team objectives, behavioural expectations or qualitative assessment instead. The CIPD’s performance-management guidance recognises these different dimensions and warns against excessive reliance on narrow numerical measures.
What happens when a performance indicator cannot be measured accurately?
Check whether the definition, data source or collection process can be improved. If reliable measurement remains impractical, choose a more observable proxy and explain its limitations. Avoid attaching strong incentives or high-stakes decisions to an indicator that employees cannot calculate consistently.
When should a business change a target instead of changing its activities?
Change activities when the objective remains relevant but execution or results need improvement. Reconsider the target when its underlying assumptions no longer hold, it encourages harmful behaviour or achieving it would no longer support the business’s priorities. Record the reason for the revision so that later performance comparisons remain meaningful.
Can a simple spreadsheet be enough to manage business KPIs?
Yes. A spreadsheet can be sufficient when it records each measure’s definition, owner, reporting period, actual result, target and resulting decision. The essential requirements are reliable data, clear accountability and regular use. More sophisticated reporting software adds little value if the underlying measures do not inform practical action.